Cómo Financiar Inversiones Inmobiliarias y Comerciales con una LLC
Como firma especializada en corretaje de préstamos comerciales e inmobiliarios (Business & Commercial Loan Broker), atendemos a diario a dos tipos de clientes: inversores internacionales que buscan rentabilizar su capital en el mercado estadounidense sin residir en EE. UU., e inversores locales que buscan escalar su portafolio comercial.
Aunque ambos perfiles tienen necesidades distintas, comparten un requisito indispensable para los prestamistas privados e institucionales: contar con una estructura corporativa sólida (LLC) para otorgar el financiamiento.
En este artículo, desglosamos cómo conseguir préstamos en EE. UU. a través de una LLC, qué opciones de financiamiento existen tanto para extranjeros como para locales y cómo nuestro equipo te ayuda a cerrar la operación sin tropiezos.
1. ¿Por qué los Prestamistas Exigen una LLC para Otorgar Préstamos de Inversión?
Si buscas un préstamo comercial, de desarrollo inmobiliario o un crédito para propiedades de alquiler, la mayoría de los prestamistas del mercado no primario (Non-QM / Private Lenders) no prestan a título personal. Requieren que la transacción se cierre a nombre de una LLC estadounidense por tres razones clave:
- Separación de Riesgo Legal: Protege los activos del prestamista y del inversor aislando el riesgo en una entidad jurídica independiente.
- Exención de Regulaciones de Consumo: Los préstamos a empresas (Business-Purpose Loans) no están sujetos a las restricciones draconianas de las hipotecas residenciales tradicionales (TRID / Dodd-Frank), lo que permite cierres más rápidos y flexibles.
- Estructura para la Ejecución: Facilita el proceso de garantías para el prestamista en caso de imprevistos sin afectar la esfera personal del prestatario.
2. Opciones de Financiamiento para Inversores Extranjeros (Non-US Residents)
Existe el mito de que sin un número de Seguro Social (SSN), visado de residencia o historial crediticio en EE. UU. es imposible obtener una hipoteca o préstamo comercial. Esto es completamente falso.
Como brokers de préstamos, trabajamos con programas especializados para inversores internacionales (Foreign National Loans):
Préstamos DSCR para Extranjeros (Debt Service Coverage Ratio)
- ¿Cómo funciona? El préstamo no se evalúa según tus ingresos personales ni tu declaración de impuestos en tu país. Se aprueba en función del flujo de caja del inmueble. Si la renta estimada cubre la cuota mensual de la hipoteca (Ratio DSCR 1:1 o superior), el préstamo califica.
- Requisitos: Pasaporte vigente, creación de una LLC en EE. UU. (ej. Wyoming o Delaware), cuenta bancaria de la empresa y reservas de capital.
- Palanca Financiera: Financiamiento de hasta un 70% - 75% LTV (Loan-to-Value) para compra o refinanciación (Cash-out).
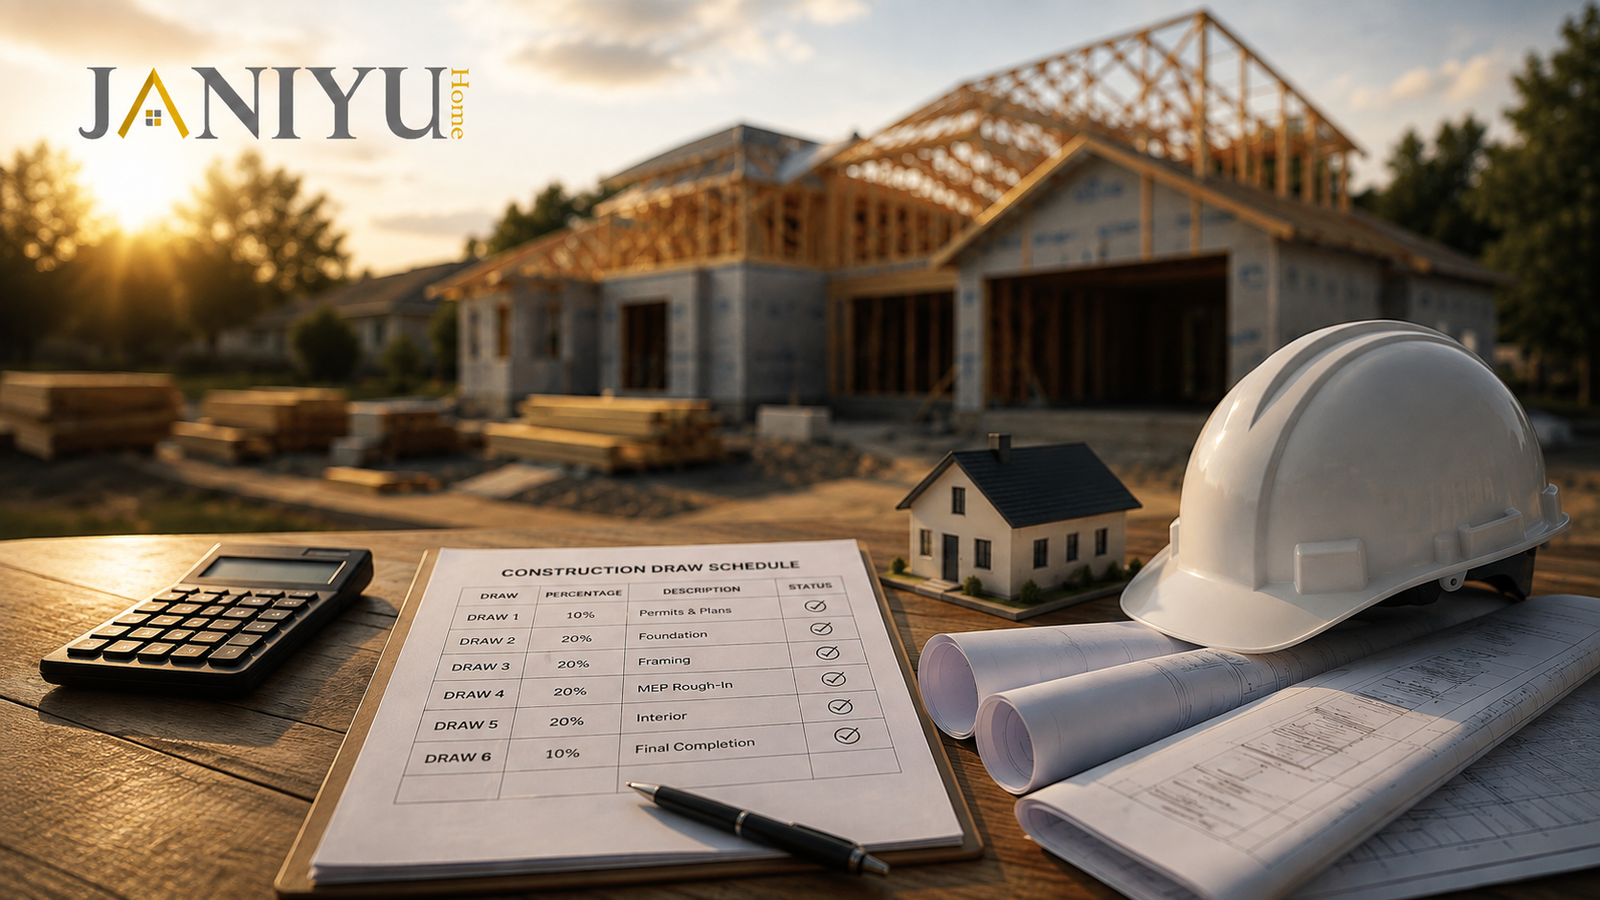
Préstamos Bridge y Hard Money (Proyectos de Remodelación o Flip)
- Diseñados para inversores extranjeros que compran propiedades para remodelar y vender (Fix & Flip) o desarrollos comerciales de corto plazo.
- Cierres rápidos en 10 a 21 días priorizando el valor tras la remodelación (After Repair Value - ARV).
3. Opciones de Financiamiento para Inversores Locales (U.S. Residents)
Para nuestros clientes residentes en EE. UU. o empresas locales que buscan capital de trabajo y expansión, la LLC permite acceder a un abanico más amplio de créditos:
- Préstamos SBA (7a y 504): Financiamiento respaldado por el gobierno federal para adquirir bienes raíces comerciales de uso propio, comprar maquinaria o financiar la adquisición de negocios con pagos a largo plazo e intereses bajos.
- Líneas de Crédito Comerciales e Inmobiliarias: Acceso a liquidez flexible garantizada por el patrimonio de la LLC para ejecutar compras rápidas.
- Préstamos DSCR y Fix & Flip Locales: Cobertura de hasta un 80% - 85% LTV aprovechando el puntaje de crédito FICO local del inversor.
4. Comparativa de Financiamiento: Extranjeros vs. Locales
| Parámetro |
Inversor Extranjero (Foreign National) |
Inversor Local (U.S. Resident) |
| Requisito de Crédito |
No requiere FICO de EE. UU. (Solo referencias o pasaporte) |
Requiere FICO (usualmente 660+) |
| Documentación de Ingresos |
No requiere impuestos ni recibos de sueldo |
Declaraciones de impuestos / P&L (salvo programas DSCR) |
| Estructura Recomendada |
LLC en Wyoming / Delaware + Holding |
LLC local o estatal estructurada |
| Porcentaje de Financiamiento (LTV) |
Hasta 70% – 75% |
Hasta 80% – 90% (según el tipo de préstamo) |
| Entidad para Cierre |
Obligatoriamente una LLC registrada en EE. UU. |
Persona Física o LLC (LLC altamente recomendada) |
5. El Rol del Business Loan Broker: Tu Aliado Estratégico
Navegar entre bancos tradicionales, prestamistas institucionales y fondos privados puede ser abrumador, especialmente si estás invirtiendo desde el exterior.
Como tus Brokers de Préstamos Comerciales, nuestro valor radica en:
- Estructurar la Operación: Verificamos que tu LLC, tu contrato de compra y tus documentos cumplan exactamente con las exigencias del underwriting del prestamista.
- Acceso a Prestamistas Wholesale: Conectamos tu proyecto con una red de más de 50 prestamistas privados que no atienden al público directo y ofrecen tarifas competitivas.
- Optimización de Tiempos: Gestionamos el proceso desde la carta de pre-aprobación (Pre-Approval Letter) hasta la firma en la agencia de títulos (Title Company).
Empieza a Financiar tu Próxima Inversión
Ya sea que residas en el extranjero y quieras adquirir tu primera propiedad de alquiler en Florida, Texas u Ohio, o seas un inversor local buscando expandir tu negocio, contar con la LLC adecuada y el programa de préstamo correcto marca la diferencia entre una operación exitosa y un rechazo bancario.
How to Finance Real Estate and Commercial Investments Through an LLC
As a firm specializing in Business & Commercial Loan Brokerage, we work every day with two main types of clients: international investors looking to grow their capital in the U.S. market without residing in the United States, and local investors seeking to expand their commercial real estate portfolios.
Although these two investor profiles have different needs, they often share one important requirement when working with private and institutional lenders: having a solid corporate structure, typically an LLC, through which the financing can be arranged.
In this article, we explain how financing through a U.S. LLC works, which loan options may be available to both foreign and domestic investors, and how our team helps structure the transaction from initial review through closing.
1. Why Do Lenders Often Require an LLC for Investment Loans?
If you are seeking a commercial loan, real estate development financing, or funding for rental properties, many Non-QM and private lenders structure their loans as business-purpose transactions and often require the property to close in the name of a U.S. LLC.
There are several reasons for this:
- Legal Risk Separation:
- An LLC helps separate the business or investment activity from the borrower's personal affairs and places the transaction within a distinct legal entity.
- Business-Purpose Loan Structure:
- Loans made primarily for business or investment purposes are treated differently from traditional owner-occupied residential mortgages. This can allow lenders to use underwriting processes designed specifically for investors and commercial borrowers.
- Clear Ownership and Collateral Structure:
- Holding the property through an LLC can simplify the legal structure of the transaction and clearly define ownership, guarantees, and collateral for the lender.
2. Financing Options for Foreign Investors (Non-U.S. Residents)
There is a common misconception that investors without a U.S. Social Security Number, U.S. residency visa, or American credit history cannot obtain real estate financing in the United States.
That is not necessarily true.
As loan brokers, we work with specialized programs designed for international investors, often referred to as Foreign National Loan Programs.
DSCR Loans for Foreign Nationals
How does it work?
Instead of qualifying primarily based on your personal salary or tax returns in your home country, many DSCR programs focus on the cash flow generated by the property.
If the property's rental income is sufficient relative to the monthly debt obligation, the property may meet the lender's DSCR requirements.
Typical requirements may include:
- Valid passport
- U.S. LLC
- U.S. business bank account
- Proof of reserves
- Property documentation
- Down payment or equity contribution
Depending on the lender, property type, borrower profile, and transaction, financing may reach approximately 70%–75% LTV for certain purchases or refinances.
Bridge and Hard Money Loans for Renovation and Flip Projects
These loans are commonly used by investors purchasing properties that require renovation before resale or refinancing.
They may be suitable for:
- Fix & Flip projects
- Short-term renovation projects
- Value-add properties
- Certain commercial or residential investment opportunities
Private lenders often place significant emphasis on the property's purchase price, project budget, borrower experience, and After Repair Value (ARV).
Because these loans are designed for investment transactions, closing times can sometimes be significantly faster than with traditional bank financing.
3. Financing Options for Local Investors (U.S. Residents)
U.S.-based investors and local businesses may have access to an even broader range of financing products.
An LLC can be used to structure investments, acquire commercial properties, and establish a business borrowing profile.
Some common options include:
SBA 7(a) and SBA 504 Loans:
Government-backed financing that may be used for qualifying owner-occupied commercial real estate, equipment purchases, business acquisitions, and other eligible business purposes.
Commercial Lines of Credit:
Flexible access to working capital that businesses may use for operating expenses, acquisitions, renovations, or other approved purposes.
DSCR Loans:
Rental property financing where qualification may rely heavily on the income generated by the property rather than traditional personal-income underwriting.
Fix & Flip Loans:
Short-term financing designed for investors purchasing and renovating properties for resale.
Depending on the loan program, borrower profile, credit score, experience, and property characteristics, domestic investors may qualify for higher leverage than foreign-national borrowers.
4. Financing Comparison: Foreign vs. Local Investors
| Parameter | Foreign Investor (Foreign National) | Local Investor (U.S. Resident) |
|---|
| Credit Requirement | Some programs do not require U.S. FICO | U.S. FICO is commonly required |
| Income Documentation | Certain programs may not require U.S. tax returns or pay stubs | Tax returns, P&L statements, or other income documentation may be required, except in certain DSCR programs |
| Typical Structure | U.S. LLC commonly used | Local/state LLC or other qualifying business structure |
| Typical Leverage | Often up to approximately 70%–75% LTV, depending on program | May reach higher leverage depending on loan type and borrower strength |
| Closing Entity | U.S. LLC is commonly required by many foreign-national investment lenders | Individual or LLC, depending on lender and loan program |
5. The Role of a Business Loan Broker: Your Strategic Financing Partner
Navigating traditional banks, institutional lenders, private lenders, and specialized investment programs can become complicated—especially when investing from outside the United States.
As your Commercial and Business Loan Brokers, our role is to help structure the financing correctly and identify the lender whose guidelines best match the transaction.
Our work typically includes:
- Structuring the Transaction
- We review your LLC, purchase contract, property information, financial documentation, and investment strategy before presenting the deal to lenders.
- Access to Wholesale and Private Lenders
- We work with a network of lenders offering financing programs for real estate investors, business owners, and commercial borrowers.
- Matching the Deal with the Right Program
- Instead of submitting the same transaction everywhere, we analyze the deal based on LTV, DSCR, ARV, borrower profile, experience, property type, and exit strategy.
- Managing the Financing Process
- We help coordinate the transaction from the initial loan analysis and pre-approval stage through underwriting, appraisal, title, insurance, and closing.
Start Financing Your Next Investment
Whether you live abroad and want to purchase your first rental property in Florida, Texas, Ohio, Pennsylvania, or another U.S. market, or you are a domestic investor looking to expand your portfolio, having the right LLC structure and the right financing program can make a major difference.
The goal is not simply to obtain a loan. It is to structure the financing so that it fits the property, your investment strategy, and your long-term objectives.